When a Family Loan Comes with an Unspoken Second Contract
Distinguish a financial agreement from guilt, loyalty tests and hidden expectations when lending money to relatives or close friends.
IN THIS ARTICLE
The amount is only one part of the exchangeA gift and a loan should not be interchangeable wordsExamine the effect on your own obligationsName the expectation that is not about moneyConsider the sibling whose yes creates a monthly argumentA refusal can preserve care without making a false promiseKeep review separate from surveillanceMake the end of the arrangement recognizableThe amount is only one part of the exchange
A relative asks for help and you begin considering the balance in your account. At the same time, another calculation is occurring: what will refusal mean about your love, loyalty or success? You may agree to a loan before deciding whether repayment is realistic. Later, resentment appears when the arrangement does not match the emotional contract you never discussed. The CyGuru reading asks you to separate these layers. A financial exchange can support a relationship, but it becomes harder to carry when money is also expected to settle belonging, gratitude or a family hierarchy. The hidden terms may be more demanding than the amount openly requested.
A gift and a loan should not be interchangeable words
If you expect repayment, say so clearly. If you intend a gift, do not later use the absence of repayment as evidence of disrespect. The CFPB recommends discussing family financial arrangements upfront and clarifying expectations, including what happens when circumstances change. That guidance supports a straightforward principle: people should know which arrangement they are entering. It does not determine what arrangement is right for every family. Cultural obligations, shared resources and individual needs differ. The useful task is to make those differences discussable before one person acts on a meaning the other person did not accept. Affection can make clarity more important, not less necessary.
Examine the effect on your own obligations
A desire to help does not erase rent, care responsibilities or other commitments you already carry. Review the effect of the proposed exchange and what would happen if repayment were delayed or never occurred. If those consequences would be serious, acknowledge them before deciding. Appropriate legal or financial advice may be needed for consequential arrangements, particularly where formal terms or local requirements matter. An essay cannot establish those rules. The doctrine adds attention to the pressure you may feel to appear capable. It should not persuade you that genuine generosity requires making your own essential obligations invisible. An offer that cannot be sustained may create a second crisis rather than resolving the first one.
Name the expectation that is not about money
Sometimes the lender privately expects more contact, obedience, access to information or gratitude expressed in a particular way. Sometimes the borrower believes that accepting help will require tolerating advice they did not request. These expectations deserve examination. A financial arrangement should not become an undisclosed transfer of personal authority. If another form of support or exchange is part of the agreement, describe it openly and ensure that participation is voluntary. Do not use a practical need as an opportunity to purchase control over someone else’s life. Equally, a borrower should not use affection to make a lender’s reasonable questions impossible to ask. Mutual clarity protects agency on both sides.
Consider the sibling whose yes creates a monthly argument
Imagine one sibling lending money for a specific expense while assuming repayment will begin as soon as the borrower returns to work. The borrower assumes repayment can wait until income feels comfortable. Neither interpretation is inherently the written agreement, because there is no written agreement. Months later, every family gathering carries an unresolved dispute. A better initial conversation would identify the amount, whether it is a loan, the proposed timing, how the parties will check in and how a change will be addressed. These details do not guarantee repayment. They create a reference point that is more reliable than reconstructing the emotional atmosphere of the original request. If repayment capacity is uncertain, the uncertainty belongs inside the decision from the beginning rather than appearing later as a surprising betrayal.
A refusal can preserve care without making a false promise
You may decide that you cannot lend. State that answer without attacking the person for asking or inventing a complicated explanation you cannot maintain. Where you genuinely can offer another kind of support, describe it accurately. Do not offer an alternative merely to remove your guilt if you cannot carry that either. The difficult emotional task is allowing disappointment to exist without treating it as proof that the decision must be reversed. This is an interpretive application of the CyGuru nervous-system lens, not a diagnosis of either person. A considerate refusal can remain uncomfortable. Comfort is not the only measure of whether conduct is fair.
Keep review separate from surveillance
If you agree to check in about repayment, use that agreed route. Constantly monitoring purchases or questioning every choice can turn the loan into a continuing contest over the borrower’s autonomy. A missed payment may need direct discussion, but suspicion about every visible expense is not the same as a defined agreement. Refer to the terms, ask about the relevant facts and document any mutually accepted revision. If the relationship becomes coercive or the amount is consequential, obtain appropriate independent guidance. Financial closeness does not remove the value of boundaries; it can make boundaries harder to see because requests are wrapped in a history of affection, sacrifice or obligation.
A scheduled conversation can also protect the relationship from becoming a series of unexpected demands. Agree on the next contact while both parties can still discuss the arrangement directly.
Make the end of the arrangement recognizable
A loan should have a clear point of completion, including what has been repaid, forgiven or revised. A gift should not return indefinitely as a claim on loyalty. The deeper Human Codes question is whether support leaves both people more able to participate honestly in the relationship. Money cannot guarantee closeness, and a written plan cannot eliminate every conflict. But an arrangement that makes its terms visible gives conflict something specific to address. That is often more respectful than expecting love to absorb every ambiguity. Help can remain generous when its limits are clear; indeed, those limits may be what allow generosity to survive beyond the urgent moment in which everyone wanted to feel that the problem was solved.
Continue the reading path
- The Energy Of Money: What meaning do you attach to money before considering what it can actually do?
- THE 33 LAWS OF MONEY: Which money principle survives when your circumstances become less comfortable?
Sources and further reading
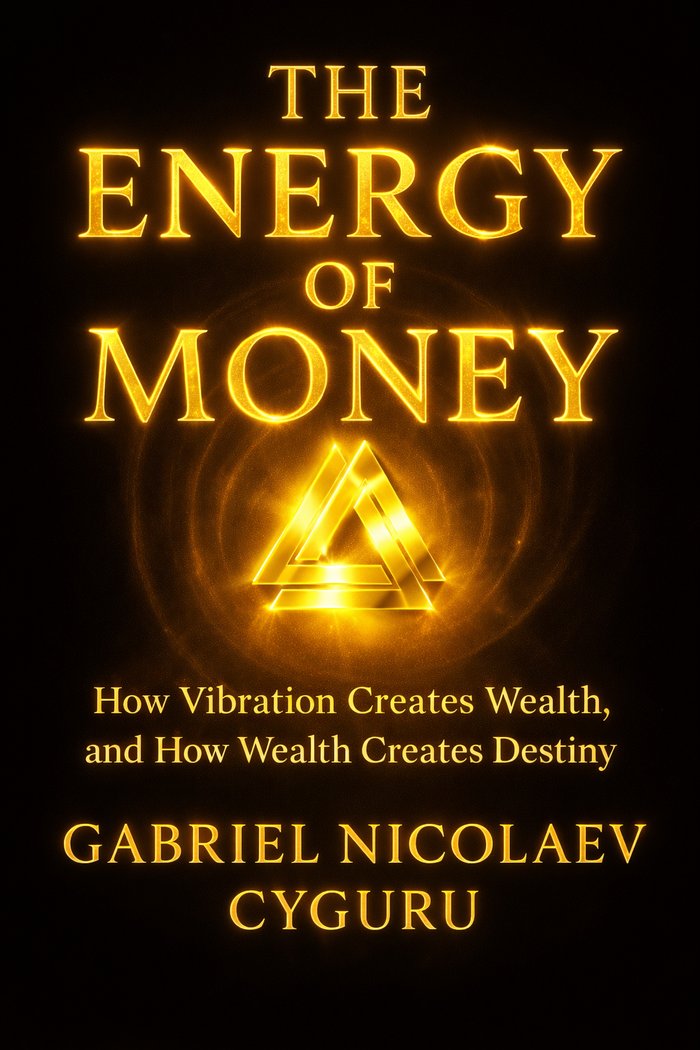
The Energy Of Money
Money carries practical value and personal meanings that are not always easy to separate. This title approaches that second layer: what wealth, scarcity, exchange and receiving can come to represent in a person’s life.
View & order on CYGURU.com ↗